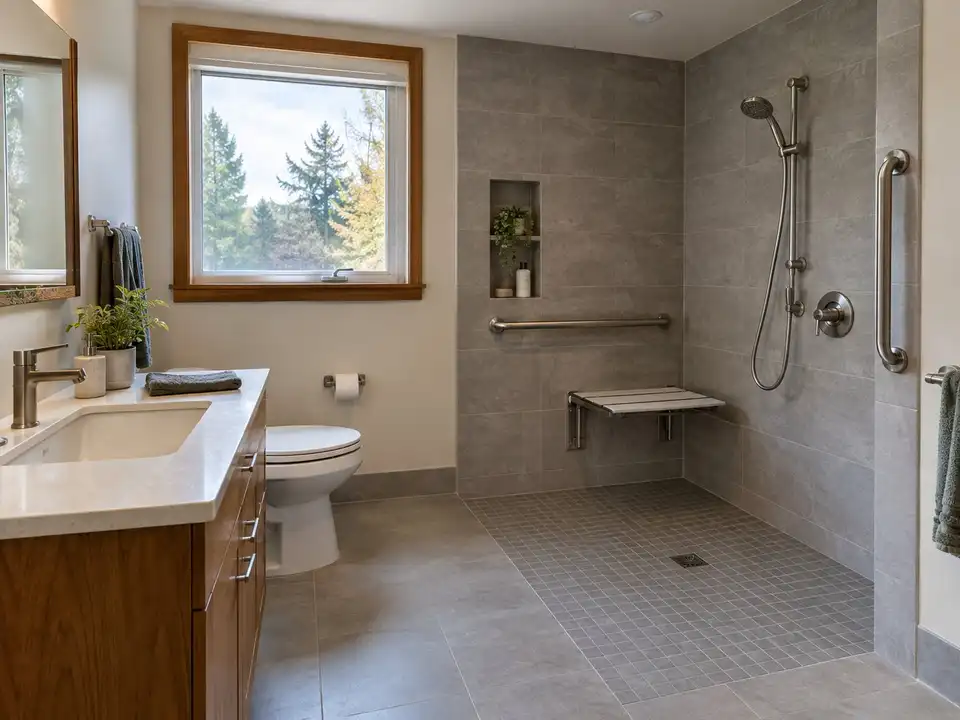
ReverseMortgageMississauga.ca explains how homeowners 55 and older can pay for accessibility renovations in Mississauga without selling. A reverse mortgage can cover a walk-in shower, a stair lift or a main-floor bedroom. There are no required monthly mortgage payments, and you keep living in the home you know.
You still pay the property taxes, home insurance and upkeep. The renovation money comes from your home’s value.
Where it starts: a free estimate
The first step is the free estimate form. It takes about 90 seconds, asks your age, your home’s rough value and what you owe, and it doesn’t affect your credit.
Next, your home is matched against every reverse mortgage lender in Canada, and the first email from Richard Hopkins, Mortgage Broker, shows how much you could get and which lenders fit, and asks how much the renovation needs. A son or daughter can be copied, and questions are answered by email, phone or video call.
Once you’ve chosen an option, you send a few documents, such as your contractor’s quotes and any occupational therapist’s recommendations. Nothing is signed before then, and you can stop at any point.
Split-levels, backsplits and stairs
Many Mississauga homes come from the city’s growth as a suburb. Erin Mills was developed from the early 1970s, and Meadowvale’s subdivisions date from the same decade (Wikipedia, Erin Mills; Wikipedia, Meadowvale).
If your home is a split-level or a backsplit, almost every room is a few steps from the next. The bathroom may be up a half flight from the kitchen, and the laundry down another.
The usual changes are a curbless walk-in shower with grab bars and a fold-down seat, a stair lift, wider doorways, and a bedroom and bathroom moved to the main floor. Each one means fewer steps between the rooms you use every day.
What help still exists, and what has ended
Ontario’s Seniors’ Home Safety Tax Credit has ended. It covered only the 2021 and 2022 tax years, at 25% of up to $10,000 in eligible expenses (Government of Ontario factsheet). The ontario.ca page now sends visitors to the Archives of Ontario.
Don’t count on a Region of Peel grant for the work. The pages for Peel Renovates, the Region’s old home repair program, have been taken down, and Peel’s second unit renovation loan is on hold and not accepting applications (Region of Peel).
The federal Home Accessibility Tax Credit is still in place. People 65 and older, or eligible for the disability tax credit, can claim up to $20,000 a year in eligible expenses for work that helps them get around the home safely or lowers the risk of harm (Canada Revenue Agency, line 31285). It is a non-refundable credit, so it reduces tax you owe.
Paying for the rest from your home
A reverse mortgage pays for the work with no required monthly mortgage payments. You can take a lump sum when the contractor starts, or part now and more later. Interest is charged only on the money you take.
Lenders check the condition of the home as part of approval. A repair that is already booked can sometimes go into the mortgage as a holdback, with the money held back until the job is complete.
If care at home is part of the plan too, paying for home care in Mississauga covers what public care provides and where monthly deposits fit.
An illustrative example: a detached home in Erin Mills
Take an illustrative couple whose younger spouse is 70, in an Erin Mills detached home worth $1,255,000, the median selling price there from April to June 2026 (53 sales) (TRREB Community Market Report, Mississauga, 2026 Q2). At 70, a reverse mortgage can reach up to about 52.85% of a home’s value, or about $663,300 on that $1,255,000 home.
They owe $60,000 on a line of credit, and that $60,000 is paid off first at closing. That leaves up to about $603,300 available, which is not extra money on top of what they owe.
They plan a curbless walk-in shower, a stair lift and a main-floor bedroom. They take only what their contractor’s written quote calls for, and interest is charged only on that. If more is needed later, they can usually ask for it.
Booked work, holdbacks and the costs
A holdback, when one is needed, is part of the same mortgage: money is set aside at closing until the booked work is done. Interest on the money you take joins the balance, at rates that ran 6.23% to 6.94% (advertised 5-year fixed rates across the four lenders, checked September 17, 2026). Home price growth often offsets some or all of that interest, and the Mississauga reverse mortgage calculator shows a balance over time.
One-time costs commonly total about $2,000 to $3,500, and independent legal advice from your own lawyer, about $800 to $1,200 in Ontario, is part of that. The Mississauga reverse mortgage cost guide breaks down each cost. Moving is the other route, and the land transfer tax and downsizing guide shows what a move within Mississauga costs.
The balance is repaid from the sale of the home, or once the last borrower moves out for good or passes away. The most you or your estate can ever owe is the fair market value of the home when the mortgage becomes due, provided the property taxes, insurance and upkeep have been kept up. This is typically called the no negative equity guarantee.
What you get when you ask for help
- A free estimate of what your home could provide for the work
- Every reverse mortgage lender in Canada compared for your home
- Every lender compared, and the best deal for your home and goals, by email
- The money timed around your contractor's written quote
- A plain check on home condition before the appraisal
- A holdback explained, if a booked repair needs one
- Family copied on every email, if you want them there
- A free referral to an independent lawyer for your legal advice
Guides to read next
- What Does a Reverse Mortgage Cost on a Mississauga Home?
- Mississauga Long-Term Care Homes: Costs and What Happens to Your Home
- Is There a Land Transfer Tax in Mississauga? What Downsizing Costs
Sources
Numbers last checked October 15, 2026.
- Government of Ontario, Seniors' Home Safety Tax Credit (redirect to the Archives of Ontario checked October 15, 2026)
- Government of Ontario, Seniors' Home Safety Tax Credit factsheet (October 27, 2022)
- Canada Revenue Agency, Line 31285: Home accessibility expenses (modified July 24, 2026)
- Region of Peel, Second unit renovations (program on hold, checked October 15, 2026)
- TRREB, Community Market Report, Mississauga, 2026 Q2 (April to June 2026)
- Wikipedia, Erin Mills (development history, checked October 15, 2026)
- Wikipedia, Meadowvale, Mississauga (development history, checked October 15, 2026)