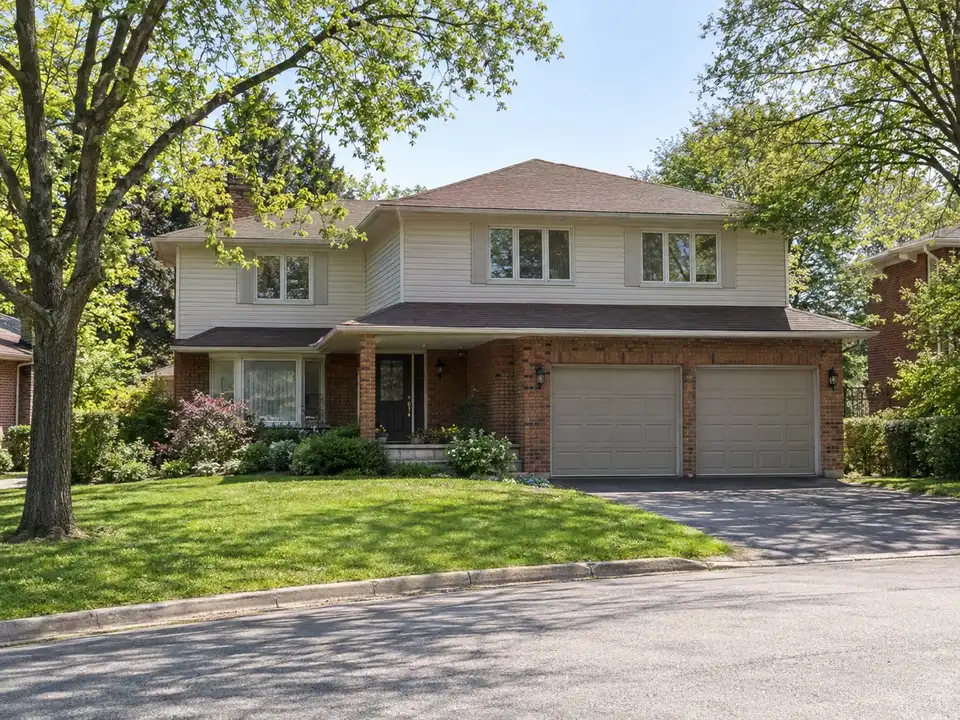
ReverseMortgageMississauga.ca helps Erin Mills homeowners 55 and older see how a reverse mortgage in Erin Mills could pay for the changes that let you stay in your house. No monthly mortgage payment is required, while the property taxes, insurance and upkeep stay on your list.
A planned community on more than 7,000 acres
Erin Mills was planned as a “new town” on more than 7,000 acres, and building began in the early 1970s (Wikipedia, Erin Mills). Erin Mills Town Centre is its main shopping centre, and Credit Valley Hospital is nearby (same source).
Highway 403 runs through Erin Mills, and the Mississauga Transitway, a bus-only road with 12 stations, runs along the 403 (Wikipedia, Mississauga).
What Erin Mills homes sold for in 2026
From April to June 2026, TRREB counted 108 sales there, with a median price of $1,027,500 across all types (TRREB Community Market Report, Mississauga, 2026 Q2).
The median price of homes that sold in Erin Mills from April to June 2026 was $1,255,000 for detached houses (53 sales), $905,000 for semis and $725,000 for condo townhouses (same source). Across all of Mississauga, the September 2026 medians were $1,219,000 for detached homes and $865,000 for semis (TRREB Market Watch, September 2026). Those are a different measure, one month across the whole city.
Making a two-storey house work for the years ahead
A house that suited a family raising children can be harder to live in later. In a two-storey house, the bedrooms and the full bathroom are often upstairs. A reverse mortgage can pay for a main-floor bathroom, a bedroom addition, wider doors or a stair lift.
Lenders check the home’s condition before they approve. If a repair is already booked, a holdback can sometimes cover it, with the money kept aside until the job is finished. Ontario’s Seniors’ Home Safety Tax Credit has ended; it covered only the 2021 and 2022 tax years (Ontario factsheet). More is in accessibility renovations in Mississauga.
Basement work the City and Region help pay for
The City’s Basement Flooding Prevention Rebate pays up to $7,500 per property (City of Mississauga):
- Sump pump: up to $6,000
- Storm backwater valve: up to $1,500, and only if your downspouts are disconnected too
- Capping foundation drains: up to $1,000
- Downspout disconnection: $125 per downspout, up to $500
You need the City’s pre-approval before any work starts, a rule in place since February 12, 2025 (same source).
The Region of Peel pays 60% of a sanitary backwater valve invoice, up to $1,500, once a building permit and inspection are done (Region of Peel). A finished basement can also become a second unit, with the permit fee refunded and registration free (City of Mississauga, additional residential units). See garden suites and basement apartments in Mississauga.
If you own the house as a couple
Both of you normally go on the mortgage and the title. If one of you passes away, nothing changes for the other: no repayment, no new approval and no deadline.
The age used can change the amount. Some lenders use the younger spouse’s age, and others use a combined age, and that one difference can be worth tens of thousands of dollars on the same house. It is one more reason every lender is compared for you.
Getting around after a hospital stay
If a disability makes MiWay hard to use, some or all of the time, Peel TransHelp offers door-to-door accessible rides. Age and income are not factors, and there is no application fee (Region of Peel, TransHelp).
Example: a main-floor bathroom at 75
For example, take an illustrative couple, the younger of them 75, in an Erin Mills two-storey detached house worth $1,255,000, the median price of Erin Mills detached homes that sold from April to June 2026. One of them came home from Credit Valley Hospital after a fall, and the stairs are now hard. They still owe $90,000 on a HELOC (home equity line of credit).
At 75, they could borrow up to about 57.75% of $1,255,000, which is about $725,000. The $90,000 HELOC is paid off first from that money. They take another $110,000 for a main-floor bathroom and bedroom (an amount chosen for this example only, not a price guide), and leave about $525,000 unused.
The HELOC payment ends, and no monthly mortgage payment takes its place. They keep paying property taxes, home insurance and upkeep. The most they or their estate can ever owe is the fair market value of the home when the mortgage becomes due, provided the property taxes, insurance and upkeep have been kept up. This limit is typically called the no negative equity guarantee.
Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada for a plan like this couple’s, with the HELOC paid off and a renovation amount worked out from the quote, and sends the best deal for your home and goals by email. Because the lender pays the brokerage once the mortgage funds, the homeowner pays nothing for the help. The one-time costs are set out in what a reverse mortgage costs in Mississauga.
What Erin Mills homes are worth, and what that means
Typical values: TRREB Community Market Report, Mississauga, 2026 Q2. The amounts are ceilings on the market's highest-lending products, rounded to the nearest $1,000, before anything owing is paid off. A lender's own appraisal sets the real figure.
From April to June 2026, the median price of homes that sold in Erin Mills was $1,255,000 for detached houses (53 sales), $905,000 for semis and $725,000 for condo townhouses. At 65, up to 50.55% means about $634,000 on the detached median, about $457,000 on the semi median and about $366,000 on the condo townhouse median. At 75, up to 57.75% means about $725,000, about $523,000 and about $419,000.
Around Erin Mills
The help is the same in every corner of Erin Mills. Here are some of the pockets and nearby communities it covers.
- Churchill Meadows
- Streetsville
- Erindale
- Clarkson
- Meadowvale
Landmarks
- Erin Mills Town Centre
- Credit Valley Hospital
- Highway 403 and the Mississauga Transitway
- Erindale GO station (Milton line), in neighbouring Erindale
- Erindale Park, on the Credit River
How the help reaches you in Erin Mills
Erin Mills homeowners deal with Richard Hopkins, Mortgage Broker, by email, phone and video call, with a son or daughter copied on every email or on a three-way call. An appraiser comes to see the house, and the one meeting you travel to is with your own lawyer: Highway 403 crosses Erin Mills, the Mississauga Transitway busway runs beside it, and MiWay is free at 65 with a PRESTO card set to the senior fare (City of Mississauga, MiWay fares).
How Erin Mills homeowners use a reverse mortgage
- Renovations to stay home: Pay for a walk-in shower, a stair lift or a main-floor bedroom from your home's value, and keep living there.
- Still paying a mortgage: Your current mortgage is paid off at closing, and there are no required monthly mortgage payments after that.
- Adding a garden suite or apartment: Pay for a garden suite or basement apartment from your home's value, for family, a caregiver or a tenant.
- Paying for care at home: Monthly deposits or a lump sum from your home's value can pay for the care hours public home care doesn't cover.